 listicle
5 Best Financial Planning Firms in Providence RI
Table of Contents
- How to Compare Financial Planning Firms in Providence RI
- What to Look For in a Providence Financial Planner
- Quick Comparison: 5 Providence Financial Planning Firms
- 1. Gorra Financial Group: Personalized Planning for Providence Families
- 2. Park Row Wealth Advisors: Providence-Area Planning and Investment Services
- 3. Cottage Street Advisors: A Providence Directory Listing
- 4. Eliot Rose Wealth Management: Named in Rhode Island Roundups
- 5. SK Wealth Management: A Rhode Island Planner to Research
- Questions to Ask a Financial Advisor Before You Hire
- Financial Advisor Fees and Compensation: What to Expect
- Retirement Planning in Providence RI: What Local Firms Offer
- Frequently Asked Questions
Last Updated: October 9, 2026
How to Compare Financial Planning Firms in Providence RI
Choosing a financial planning firm in Providence RI comes down to one question: does the firm's model match what you actually need? This guide from Gorra Financial Group walks through Providence-area options, what each does well, and the questions that separate a good fit from an expensive mismatch.
Financial planning is the ongoing process of organizing your income, investments, insurance, taxes, and estate wishes into one coordinated strategy that changes as your life does. That definition matters here, because the firms below differ less in what they call themselves than in how they get paid and who they serve.
Below, we break down each firm, then give you a fee framework and a question list you can take to any first meeting. Most people who feel stuck aren't missing information. They're missing a way to compare.
What to Look For in a Providence Financial Planner
Start with three things: how the firm is paid, whether its credentials match your situation, and whether it will put a plan in writing. Everything else is secondary.
Fiduciary status is a legal standard, not a marketing badge. Registered investment advisers owe a fiduciary duty; broker-dealers generally operate under a suitability standard. Some professionals hold both roles, and the distinction can shift depending on the account. Ask which capacity applies to you.
Credentials worth understanding:
- CFP® indicates coursework, experience, and a fiduciary commitment in the planning engagement.
- CPA signals tax expertise. Tax advice should come from the licensed provider, not be assumed from a planning relationship.
- Registered Representative means the person can sell securities through a broker-dealer.
A common mistake is choosing a firm based on a single meeting's rapport. What most guides miss is that fit shows up in the details: who returns your calls, how often you review the plan, and whether the firm explains its compensation before you sign.
Quick Comparison: 5 Providence Financial Planning Firms
The table below summarizes what the available public information shows for each firm. Where details aren't publicly verified, we say so rather than guess.
| Firm | Publicly Listed Focus | Providence Connection | Pricing Transparency | Best For |
|---|---|---|---|---|
| Gorra Financial Group | Comprehensive planning, insurance, retirement income | Core local market | Discussed directly with the firm | Families and business owners wanting a personalized plan |
| Park Row Wealth Advisors | Planning and investing services, advisor costs | Providence page | Page covers services and costs | Readers with fee questions up front |
| Cottage Street Advisors | Listed as a Providence financial planner | Providence directory listing | Not shown publicly | Early-stage local research |
| Eliot Rose Wealth Management | Named in a Rhode Island roundup | Providence not verified | Not shown publicly | Statewide shortlist building |
| SK Wealth Management | Named in a Rhode Island roundup | Providence not verified | Not shown publicly | Comparing Rhode Island options |
1. Gorra Financial Group: Personalized Planning for Providence Families
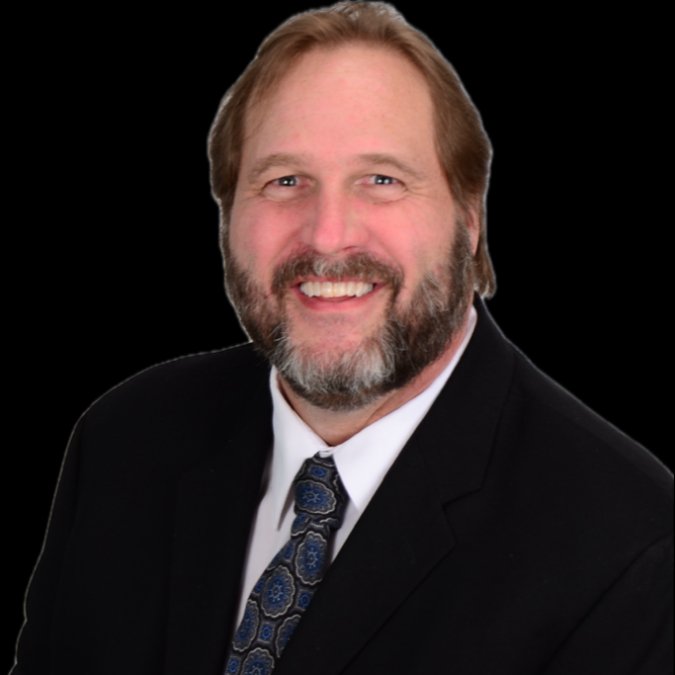
Gorra Financial Group is a Providence-based financial planning firm built around personalized, legacy-driven strategies for individuals, families, and business owners. The firm's stated approach centers on data-driven planning and a road map written around your goals, not a model portfolio handed to everyone.
Services and Approach
GFG works with clients on retirement income planning, life insurance, wealth management, legacy planning, long-term care planning, Medicare education, and employee benefits. The firm also supports English- and Spanish-speaking clients.
One detail worth understanding: GFG states that it offers access to more than 100 companies for investment and insurance options. That matters because comparing available providers can help you evaluate fit, costs, and features side by side. It does not mean every advisor offers every provider, and it does not mean every company is highly rated. Ask which carriers are actually available for your situation.
GFG is not itself a broker-dealer or a registered investment adviser. Advisory and securities services are offered through registered representatives and investment adviser representatives on staff, and the firm is a general agency appointed with the insurance companies of OneAmerica Financial®. Joshua Gorra leads the firm, with Heriberto Gonzalez, CPA, and Kenneth O'Connor, CFP® on the team.
Who It's Best For
GFG fits Providence-area families and business owners who want one coordinated plan rather than a stack of separate accounts. If your personal finances and your company's finances are tangled together, or if you're approaching retirement and want a written income strategy, that's the profile this firm is built for.
Where it may not fit: if you want a purely self-directed, low-touch relationship, a full planning engagement is more than you need.
Schedule a Financial Planning Conversation →
2. Park Row Wealth Advisors: Providence-Area Planning and Investment Services
Park Row Wealth Advisors maintains a Providence, Rhode Island page that discusses financial advisor services and costs.
Services and Approach
The firm's Providence page describes help with planning, investing, and preparing for the future. That's a broad description, and the public information doesn't list specific service tiers or engagement terms. Costs are addressed on the page itself.
Who It's Best For
Readers who want to understand the fee conversation before committing to a meeting. If you're earlier in the process and still deciding whether to work with an advisor at all, a firm that publishes cost context is a reasonable first call.
The limitation is depth. Without published service details, you'll need to ask directly what a planning engagement includes and how often you'd meet.
3. Cottage Street Advisors: A Providence Directory Listing
Cottage Street Advisors appears in a Providence financial-planner directory.
Services and Approach
The directory lists the firm among Providence financial planners. It does not describe the firm's services, fees, or engagement model. One caution: directory pages sometimes display general hourly-rate language that applies to the directory as a whole, not to a specific firm. Don't assume a listed rate belongs to Cottage Street Advisors until the firm confirms it.
Who It's Best For
Providence residents building an initial shortlist. Treat this as a name to research directly rather than a recommendation. Call, ask what a typical engagement looks like, and compare the answer against the other firms here.
4. Eliot Rose Wealth Management: Named in Rhode Island Roundups
Eliot Rose Wealth Management is named in a Rhode Island financial-planner roundup.
Services and Approach
The roundup identifies it as a financial-planning firm but doesn't specify its services or engagement model. That's the pattern with most roundup listings: they establish that a firm exists and operates in the state, not what working with it is like.
Who It's Best For
Readers willing to widen their search beyond Providence proper. If you commute into the city or live in a surrounding Rhode Island community, a statewide shortlist can surface options a city-only search misses. Confirm location and service area directly before you invest time in a meeting.
5. SK Wealth Management: A Rhode Island Planner to Research
SK Wealth Management appears in the same Rhode Island roundup, described as a financial advisor option without further detail on services or fees.
Services and Approach
The listing doesn't cover pricing, services, or client engagement. It simply means the public record is thin.
Who It's Best For
Readers who prefer to compare several Rhode Island firms before narrowing down. Use it as one data point, then verify credentials, compensation, and service scope the same way you would with any firm on this list.
Questions to Ask a Financial Advisor Before You Hire
Ask these before you share account details or sign anything. The answers tell you more than any brochure.
Schedule a Financial Planning Conversation →
- Are you acting as a fiduciary for this engagement, and in what capacity?
- How are you compensated, and who pays you?
- What does a written plan include, and how often is it reviewed?
- What happens if my situation changes mid-year?
- Which providers would you consider for my situation, and why those?
- Who else on your team would I work with day to day?
- How do you handle tax questions, and who provides that advice?
- What would make you tell me I'm not a good fit?
Question two is the one people skip, and it's the one that matters most. Compensation shapes recommendations, and understanding it doesn't mean distrusting your advisor. It means knowing what you're buying.
Financial Advisor Fees and Compensation: What to Expect
Financial advisor fees and compensation generally fall into a few structures: a percentage of assets under management, a flat or hourly planning fee, commissions on insurance or investment products, or some combination. Each creates different incentives.
Asset-based fees scale with your portfolio, so the cost rises as your balance grows. Flat fees are predictable and don't change with account size. Commission-based arrangements pay the professional when a product is sold, which is common in insurance and can be appropriate when the product itself is the goal.
The right question isn't which model is cheapest. It's which model fits your situation and whether the firm will explain it clearly. Ask for the total cost in writing, including any product-level charges that sit outside the advisory fee. If a firm can't give you a straight answer, that's your answer.
Retirement Planning in Providence RI: What Local Firms Offer
Retirement planning in Providence RI typically covers income sequencing, Social Security timing, health care costs before Medicare eligibility, and legacy wishes. Local firms differ mainly in how much of that they handle under one roof.
The sequence matters more than most people expect. When you draw from accounts in the wrong order, you can pay more in tax than necessary, and the mistake compounds over decades. A written income plan addresses the order, the timing, and the what-ifs.
If you're within a few years of retiring, bring three things to your first meeting: your most recent statement for every account, your expected Social Security benefit, and a rough monthly spending figure. Firms can work without them, but the conversation gets specific much faster with them.
Comparing financial planning firms in Providence is really a comparison of fit: how each one gets paid, who it serves, and whether it will put your plan in writing. At Gorra Financial Group, we build personalized, legacy-driven strategies using a data-driven planning approach, and we offer access to more than 100 companies for investment and insurance options so you can weigh fit, costs, and features with an advisor. Call 401-228-8804 or email info@gorrafinancial.com to schedule a time with our firm and start with a conversation about where you are and where you want to be.
Frequently Asked Questions
How do I choose a financial planning firm in Providence, RI?
Start by identifying your goals: retirement income, estate planning, business finances, or all three. Then check each firm's services, credentials, and fee structure. Ask whether the advisor is a fiduciary, how they are compensated, and whether they have experience with clients like you. Meeting with two or three firms before deciding is standard practice. GFG offers a no-obligation conversation to discuss your situation.
What services do financial planning firms in Providence offer?
Most Providence firms provide retirement planning, investment management, estate and legacy planning, and insurance guidance. Some also help with tax coordination, business succession, and employee benefits. GFG works with individuals, families, and business owners on retirement income, life insurance, wealth management, legacy planning, and Medicare education. Service menus vary by firm, so confirm what each one handles before you commit.
How do financial advisors charge for their services?
Common models include a percentage of assets under management, flat or hourly fees, and commissions on insurance or investment products. Some advisors use a combination. The right model depends on your situation and how much ongoing support you want. Ask each firm to explain all compensation sources in writing. GFG discusses fees and compensation openly during the initial conversation.
What questions should I ask a financial advisor before hiring them?
Ask about their credentials, whether they act as a fiduciary, how they are paid, and what conflicts of interest exist. Request a sample financial plan and ask how often you will meet. Find out who else on the team will handle your account. Also ask how they measure progress toward your goals. A good advisor welcomes these questions and answers them clearly.
Can a financial planner help with retirement income and legacy planning?
Yes. Retirement income planning focuses on turning savings into reliable income, coordinating Social Security, pensions, and withdrawals. Legacy planning addresses how you pass assets to heirs, including beneficiary designations, life insurance, and estate strategies. GFG specializes in legacy-driven planning for Providence-area families and can coordinate with your attorney or CPA as needed.